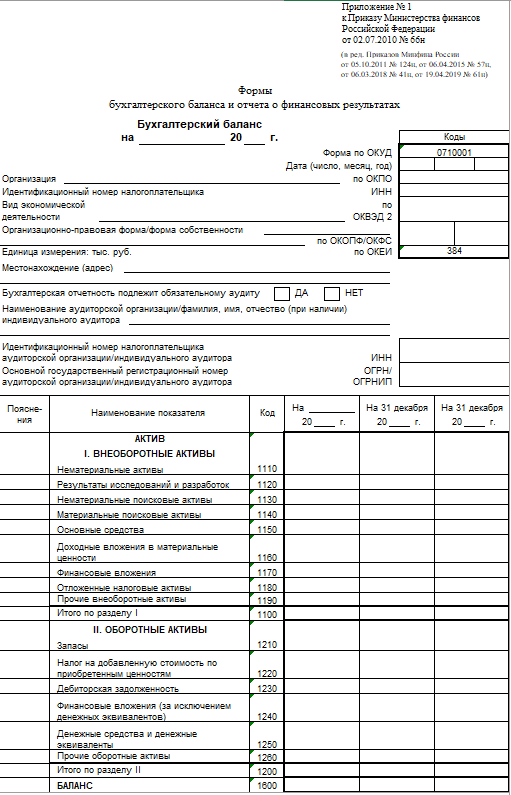
balance sheet
accounting financial summary
Press Enter · cited answer in seconds
0 sources
balance sheet
Summary
balance sheet ranks in the top 2% of general entities by monthly Wikipedia readership (564 views/month).[1]
Key Facts
- balance sheet is a type of financial statement[2].
- balance sheet is part of double-entry bookkeeping[3].
- balance sheet is part of tax law[4].
- balance sheet is part of general economics[5].
- balance sheet is part of financial accounting[6].
- balance sheet's Commons category is recorded as Balance sheets[7].
- balance sheet's pseudonym is recorded as statement of financial position[8].
- balance sheet's pseudonym is recorded as statement of financial status[9].
- balance sheet's topic's main category is recorded as Category:Balance sheet[10].
- balance sheet's facet of is recorded as accounting terminology[11].
- balance sheet's described by source is recorded as Brockhaus and Efron Encyclopedic Dictionary[12].
- balance sheet's described by source is recorded as Otto's encyclopedia[13].
- balance sheet's described by source is recorded as Great Soviet Encyclopedia (1926–1947)[14].
- balance sheet's described by source is recorded as Great Soviet Encyclopedia (1926–1947)[15].
- balance sheet's described by source is recorded as Great Soviet Encyclopedia (1926–1947)[16].
- balance sheet's described by source is recorded as Collins English Dictionary[17].
- balance sheet's different from is recorded as heritage designation[18].
- balance sheet's P14541 is recorded as 4PC12a[19].
Body
Definition and Type
balance sheet is a type of financial statement[2].
Use and Application
Part of include double-entry bookkeeping[3], a bookkeeping system[20]; tax law[4], an area of law[21]; general economics[5], a branch of science[22]; and financial accounting[6], a field of work[23].
Why It Matters
balance sheet ranks in the top 2% of general entities by monthly Wikipedia readership (564 views/month).[1] It has Wikipedia articles in 30 language editions, a strong signal of global cultural recognition.[24] It is known by 90 alternative names across languages and contexts.[25]